



Agricultural producers, within the limits of their obligations established by the legislation of Ukraine, must carry out:
- timely payment of environmental tax for emissions of pollutants into the atmosphere
- rent for special water use,
- submission of statistical reports on emissions (report 2-TP air), water use report 2-TP water management report, report № 7-GR (groundwater) and waste declarations.
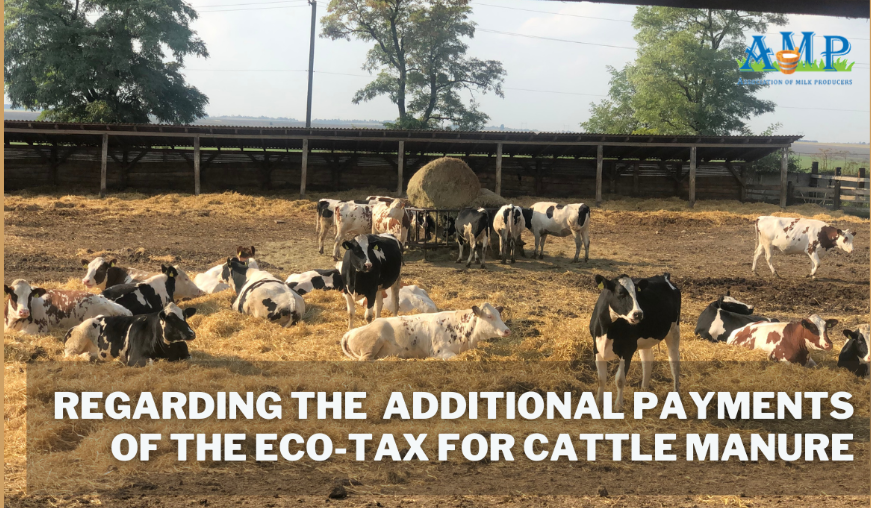
Manure is not waste and its location or further disposal is not subject to taxation in accordance with Article 240.1.3 of the Tax Code of Ukraine (TCU).
The tax authority may justify the requirements for additional payment of the eco-tax by the fact that manure is a waste and is in the State Classification of Waste. However, the Law of Ukraine "On Waste" does not apply to relations in the field of treatment of animal by-products not intended for human consumption and does not define the concept of "manure".
The definition of "manure" is contained in the Law of Ukraine "On animal by-products not intended for human consumption." According to this law: "manure - any excrement and / or urine of farm animals, except fish, with or without litter." Especially if the company uses manure as organic fertilizers.
After analyzing the case law on the same issue, it is obvious that the courts come to the conclusion that manure is not a waste.
Therefore, the attribution of manure to waste by the controlling body and the obligation to impose an environmental tax is unfounded and does not meet the requirements of tax legislation.
Until January 1, 2013, agricultural enterprises, farms and other farms that were engaged in the production (growing) of livestock and poultry products, and at the same time disposed of waste (manure and poultry manure) during the reporting quarter, were payers of environmental tax.
From January 1, 2013, the Code changed the meaning of the concept of "waste disposal", and therefore eliminates double taxation of environmental tax.
Press service of the Association of Milk Producers